Africa’s financial inclusion agenda is entering an important new phase. While expanding access to banking, digital payments and financial services remains essential, the greater opportunity lies in connecting these services to meaningful economic participation, enterprise growth and cross-border trade.
For millions of African entrepreneurs and small businesses, having access to a financial account is only the beginning. The real measure of inclusion is whether that access enables them to receive payments, secure financing, trade across borders and build sustainable enterprises.
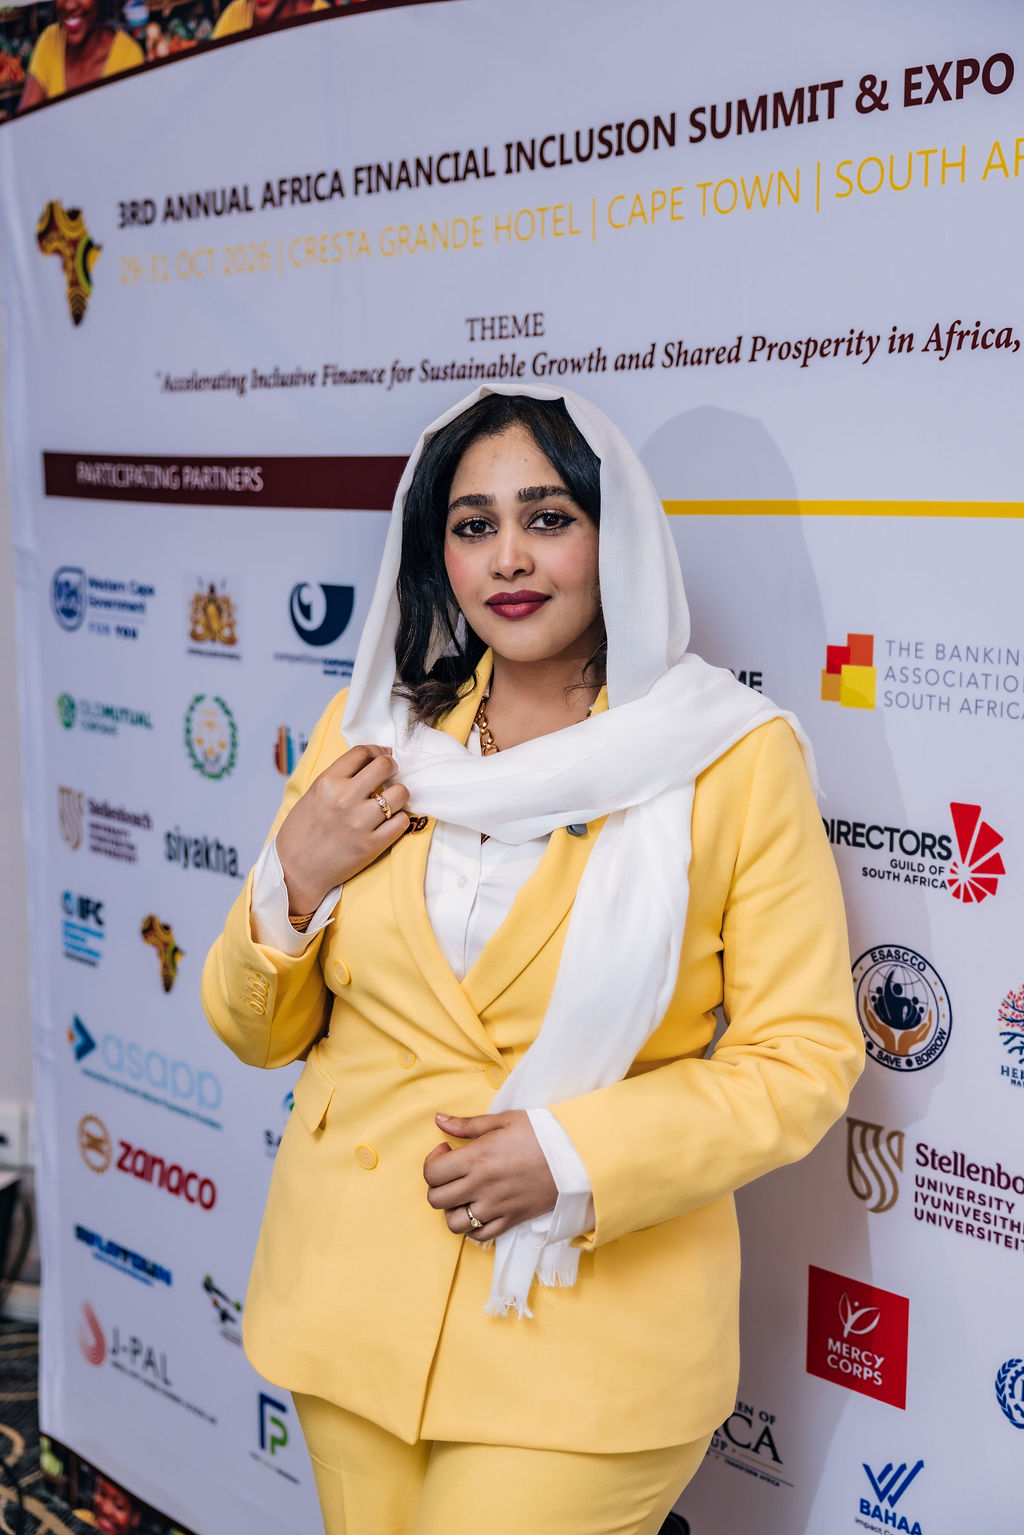
These issues were central to discussions at the 3rd Annual Africa Financial Inclusion Summit and Expo, which brought together stakeholders from across the financial services ecosystem to examine the future of financial inclusion and economic participation.
Among the contributors was Dr Assjad Al-Kazem, Founder and CEO of ASD Solutions, Qatar, who participated in the Summit as both a keynote speaker and panelist, sharing perspectives on financial inclusion, technology, business growth and the importance of collaboration between markets.
For Dr Al-Kazem, the next phase requires closer cooperation between financial institutions, technology providers, governments and the private sector.
“Access alone is not enough. People need financial services they can trust, afford and actually use in their everyday lives,” she explains. Her perspective reflects a broader shift in how financial inclusion should be understood: not simply as access to financial products, but as the ability to use them to create economic value.
Moving Beyond Access to Economic Participation
Africa has demonstrated the transformative potential of digital financial services. Mobile money, fintech innovation and digital payment platforms have expanded access for individuals and businesses historically underserved by traditional banking systems.
However, significant opportunities remain in connecting these services.
For small and medium-sized enterprises (SMEs), payments, business information, financing and market access are interconnected. Digital transactions can generate valuable business records which, when appropriately verified and assessed, may help financial institutions better understand an enterprise's commercial activity and potential creditworthiness.
Dr Al-Kazem believes the industry must increasingly focus on practical outcomes.
“We should measure success by whether a small business can receive payments, access suitable finance and grow — not simply by how many accounts we open.”
This requires financial institutions and policymakers to look beyond traditional access metrics and consider how financial services contribute to enterprise development, employment and sustainable economic participation.
Trust, Technology and the Future of Financial Services
As financial institutions increasingly adopt artificial intelligence and digital technologies, the reliability of information used to make decisions is becoming more important. More data does not necessarily produce better decisions. Financial institutions frequently work with fragmented information across different systems and sources. The challenge is determining what information can be trusted, how it can be verified and how it can support responsible decision-making.
This is an area Dr Al-Kazem is exploring through TrustAI, an initiative focused on helping financial institutions turn fragmented information into traceable evidence.
“The challenge is determining what information can be trusted, how it can be verified and how it can be transformed into useful evidence,” she says.
As artificial intelligence becomes more influential in financial services, transparency, accountability and reliable information will be essential to maintaining confidence in financial institutions and the decisions they make.
Connecting Africa’s SMEs to Regional and Global Markets
One of the most significant opportunities lies in making it easier for African businesses to participate in regional and international trade.
Africa's diverse markets offer considerable commercial potential, yet businesses continue to navigate differences in currencies, regulatory frameworks, payment infrastructure and financial systems.
For smaller enterprises, these barriers can make cross-border trade particularly challenging.
Dr Al-Kazem sees an opportunity to connect digital payments, trusted business information and financial services into a more integrated ecosystem.
“Imagine a small business that can sell across borders, receive payments reliably and use its transaction history to support a financing application. That creates value throughout the entire business journey.”
Such an approach could help SMEs demonstrate commercial performance, strengthen their financial visibility and potentially unlock access to appropriate financing. The opportunity extends beyond developing another fintech application. It is about building the financial infrastructure that allows African enterprises to compete more effectively in regional and global markets.
Strengthening Qatar–Africa Business Connections
The relationship between Qatar and Africa presents further opportunities for investment, enterprise development and commercial partnerships.
Qatar's investment capabilities and international business relationships offer potential avenues for collaboration with African markets, particularly across finance, technology, infrastructure and enterprise development.
However, meaningful partnerships require more than capital. They need local market knowledge, credible business partners, technical expertise and a clear understanding of commercial opportunities.
Dr Al-Kazem believes stronger connections between business leaders in both regions could translate into practical commercial outcomes.
“I’m particularly interested in creating stronger connections between women business leaders in Qatar and Africa, leading to practical trade and investment opportunities.”
This presents an opportunity to develop relationships that go beyond networking, creating structured pathways for women entrepreneurs, investors and business leaders to collaborate, access markets and pursue new ventures.
The Importance of Regulatory Clarity
Innovation in financial services must also be supported by predictable regulatory environments.
As digital payments, artificial intelligence and cross-border financial services evolve, governments and regulators face the challenge of balancing innovation with consumer protection, cybersecurity, data governance and financial stability. For businesses and investors, understanding the regulatory environment is essential.
Dr Al-Kazem argues that greater predictability can encourage investment and strengthen cooperation between financial institutions and technology providers.
“When we reduce uncertainty, we give businesses more confidence to invest, build and grow.”
The objective should not be weaker regulation, but clearer frameworks that enable responsible innovation while maintaining the integrity of financial systems.
Turning Africa’s Potential into Measurable Value
Africa's ability to translate its economic potential into sustainable prosperity will depend partly on how effectively it connects capital, technology, institutions and markets.
Financial inclusion must therefore become part of a broader economic development strategy.
For entrepreneurs, this means building businesses that can demonstrate value, establish trust and access appropriate markets and financing.
For investors, it means identifying capable teams and supporting enterprises with credible growth strategies.
For financial institutions, it means developing services that respond to the practical needs of businesses and communities.
For policymakers, it means creating environments in which innovation, investment and cross-border commerce can flourish.
Dr Al-Kazem's message is ultimately one of ambition, collaboration and disciplined execution. “Build with ambition, but execute with discipline. Solve a problem that matters and earn the trust of your customers.”
Africa's next financial inclusion chapter will not be defined by a single technology or financial product. It will depend on creating interconnected systems that allow businesses to become more visible, more bankable and more competitive.
The real measure of financial inclusion will not simply be how many people enter the financial system, but how many are empowered to build, trade, invest and create lasting economic value.
Revised article supplied to Africa Rising TV. By Oliver Chikodzore, with insights from Dr Assjad Al-Kazem.